It is going to be another week filled with challenging macro-political and earnings events for investors in the United States, including tech hardware and semiconductor news, the much-awaited jobs report, and the midterm elections. Tech hardware and software titans aim to restore investor confidence following the tough week when tech stocks were selling off amid fears about capital efficiency and hyperscalers' spending pressures.
Now that the Federal Reserve maintained rates on hold at its last month's meeting, the focus has now shifted to the economy's resilience and the Fed's future monetary policy outlook. Friday's Non-Farm Payrolls Employment Change is this week's critical macro event that will help decide whether the American job market is hitting the non-inflationary level or sliding into structural weakness.
Recapping the Markets Last Week
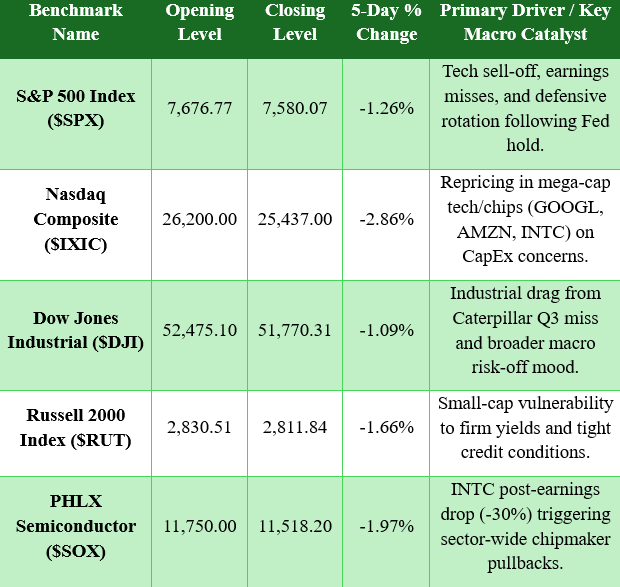
The U.S. equities experienced significant declines last week after the valuation readjustment in technology leaders sent shock waves across all markets. The S&P 500 Index slumped by 1.26% to 7,580.07, with the tech-focused Nasdaq dropping 2.86% to 25,437.00 amid poor earnings and negative free-cash-flow developments in the megacaps.
The industrial and small-cap indices were also affected by the sell-off pressure. The Dow Jones Industrial Average dropped 1.09% to 51,770.31 amid a disappointing construction equipment sales performance reported by Caterpillar in Q3. The Russell 2000 lost 1.66% to 2,811.84 owing to high government bond yields. Communication Services (XLC) was the worst-performing sector (-6%) of the week, while the defensive Real Estate (XLRE) (+2.1%) outperformed.
Major Market Benchmarks Performance (Prior 5 Trading Days)
Fixed Income, Commodities & Currency Baseline
10-Year Treasury Yield (US10Y): Decreased 5 bps to 4.980% and fell below the 5.00% level in response to safe-haven demand.
2-Year Treasury Yield (US2Y): Fell 9 bps to 4.610% in light of a rate hold by the Fed.
2Y/10Y Yield Curve Spread: Steeper to +0.380% (+6 bps widening).
WTI Crude Oil: Added +0.82% to $104.12/bbl due to worries about OPEC Middle East supplies.
Brent Crude Oil: Declined -3.22% to $113.43/bbl after talks about oil reserves release.
US Dollar Index (DXY): Ranged around 101.80 (+0.10%).
Upcoming Important Earnings & Economic Events
This week will see a jam-packed schedule of earnings along with key economic data points.
Monday is kicking off with reports from Apple (AAPL), Palantir (PLTR), Vertex (VRTX), and Marriott (MAR).
Tuesday will have U.S. Midterm Elections and reports from Advanced Micro Devices (AMD), Shopify (SHOP), Pfizer (PFE), and Super Micro Computer (SMCI).
Wednesday is set to deliver earnings from Novo Nordisk (NVO), McDonald's (MCD), Qualcomm (QCOM), and Arm Holdings (ARM).
ConocoPhillips (COP) and Airbnb (ABNB) will be reporting on Thursday, and Moderna (MRNA) will report on Friday.
Economic data will start on Monday and Wednesday with manufacturing and services ISM indices.
Thursday will deliver preliminary Q3 Nonfarm Productivity and Unit Labor Costs along with jobless claims data.
This week will end with key October Nonfarm Payrolls and Unemployment Rate data release.
Key Market Catalysts to Watch This Week
Tech Spend as Apple, AMD, ARM Report This Week
After negative reactions to hyperscaler CapEx last week, the market will now focus on margins on consumer hardware, AI spending from enterprises, and license revenue dynamics for semiconductor companies.
Apple (AAPL): Will report Monday after the close; earnings are expected to come in at EPS of $2.00 (+8.11% YoY) on revenues of $113.40B (+10.23% YoY); options trading implies a potential ±4.2% earnings swing.
Advanced Micro Devices (AMD): Reports Tuesday; AMC consensus earnings of $1.97 on revenues of $6.72B, with an ±8.8% earnings swing implied.
Qualcomm (QCOM) & Arm Holdings (ARM): Both reporting side by side on Wednesday, with AMC facing a high-stakes test for mobile processor license revenue.
Overall S&P 500 Earnings Growth Began to Expand
Despite the volatile tech mega-caps, the overall corporate earnings are still strong. Aggregate Q3 2026 earnings growth for S&P 500 stands at +30.2% YoY with +13.4% revenue growth. That is the third straight quarter with the +25% earnings expansion bar.
While the Magnificent Seven saw aggregate Q3 earnings growth of +33.2%, when isolated NVIDIA (+91.5% EPS growth) from this group and looked at "Mag-6" (+18.7%), they actually underperformed the rest of the market (S&P 493 at +27.7%).
Macro Shift: Elections Uncertainty & Jobs Data
While the Federal Reserve held its benchmark target rate at 3.75%–4.00% at the October meeting, futures pricing is signaling a hawkish stance for December.
According to CME FedWatch data, there is a 70.7% chance of a 25 bps rate hike at the December 8–9 meeting amid persistent inflation data (September CPI at 3.7%, PPI increased 6.3% YoY).
On Friday, the October Non-Farm Payrolls report will become key. After weak September job creation of 29,000 jobs, consensus is looking for +65,000 job additions and a flat Unemployment Rate at 4.2%.