U.S. investors face a week full of crucial inflation indicators, an avalanche of financial reports by top companies in cloud infrastructure and semiconductor space, and market assessment of the U.S. midterm elections results. The equity markets are emerging from a significant de-risking process when AI infrastructure stocks experienced heavy algorithmic selling, and macroeconomic policy shifts caused some turbulence in several industries.
With the Fed keeping its interest rate unchanged at 3.75%–4.00% and maintaining its hawkish stance on monetary policy, the market will be focusing on the October CPI release on Tuesday and PPI numbers on Friday to assess the trajectory of terminal rates. Good labor market numbers increased chances of a rate hike at the December FOMC meeting.
Last Week Market Recap
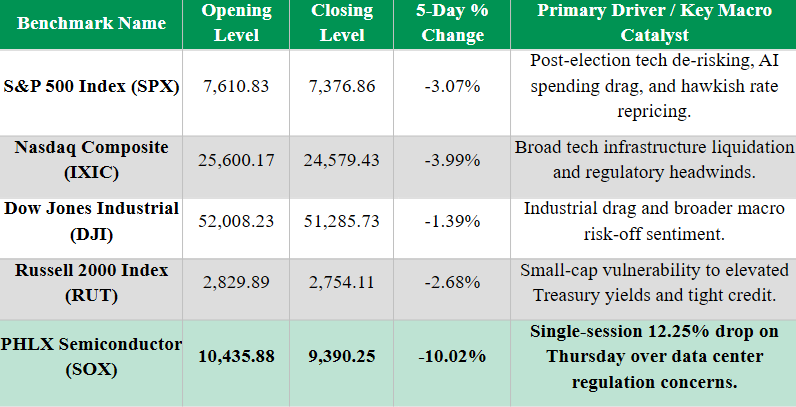
The U.S. equities markets booked sizable declines last week, breaking multi-week gains amid election aftermath and a dramatic correction in large-cap tech stocks. Specifically, the S&P 500 index fell 3.07% to finish at 7,376.86, while the tech-laden Nasdaq Composite shed 3.99% to finish at 24,579.43 following valuations re-calibration among artificial intelligence (AI) and semiconductor infrastructure companies.
Broader selling pressure spilled into the industrials and small caps index as well. The blue chip Dow Jones Industrial Average was down 1.39% at 51,285.73, while the small cap Russell 2000 fell 2.68% at 2,754.11 on growing yield expectations that adversely impacted credit markets. The PHLX Semiconductor Sector Index (SOX) declined sharply 10.02% week-to-date, including a 12.25% plunge in one day (Thursday) due to regulations weighing on deployment prospects in data centers. Defensive sectors like Consumer Staples (XLP, +5.02%) and Health Care (XLV, +3.45%) outperformed last week on defensive rotation flows.
Major Market Benchmarks Performance (Prior 5 Trading Days)
Fixed Income, Commodities & Currency Baseline
10-Year Treasury Rate (TNX): Rallying after the strength in job numbers and settled at 4.86% post safe-haven buying on mid-week.
2-Year Treasury Rate (UTWO): Closing at 4.51%, reflecting higher probability of future tightening by the central bank.
2Y/10Y Curve Spread: Widening to +35 basis points (+3 basis points over the week).
WTI Crude Oil: Slumped -5.84% to $90.83/barrel post midterms geopolitical shifts expectation.
Brent Crude Oil: Slammed down -16.42% to $98.32/barrel as the geopolitics-induced premium unwound.
Gold Spot (XAU/USD): Rallying up +4.51% to $4,039.00/oz due to resumption of safe-haven buying.
U.S. Dollar Index (DXY): Rallying +0.54% to 102.30, supported by strength in payrolls and yield rates.
This Week’s Key Earnings and Economic Events
This week’s list of corporate reporting will include major infrastructure plays, high beta technology stocks, and cyclical energy stocks. Monday will see reports from KKR & Co. (KKR) and Constellation Energy (CEG) BMO, Rocket Lab (RKLB), Take-Two Interactive (TTWO) and Occidental Petroleum (OXY). The next day will be marked by Sea Ltd (SE) and CoreWeave (CRWV) along with the highly anticipated October CPI release. Thursday will include Applied Materials (AMAT), Cisco Systems (CSCO), and Nu Holdings (NU) AMC.
Key Market Catalysts to Watch This Week
Semiconductor Capital Equipment and Infrastructure Focus
After a rough week for semiconductor and hardware companies, the attention of Wall Street moves on semiconductor manufacturing tools and enterprise networking execution.
Applied Materials (AMAT): Announcing Thursday after the market close, with expectations of EPS at $4.06 (+87.1% YoY) with revenues at $10.30B (+51.5% YoY). The WFE demand and HBM tool deployment will be in focus for the analysts.
Cisco Systems (CSCO): Reports Thursday AMC, with expectations of EPS at $1.32 (+32.0% YoY) and revenues at $18.11B (+21.7% YoY). Expectations of enterprise AI Ethernet switching and hardware gross margins will be the focus.
CoreWeave (CRWV): Cloud GPU provider, CoreWeave is scheduled to announce Tuesday, with expectations of net loss of -$1.18 per share with revenues of $3.50B. Expectations will depend on enterprise GPU cloud booking backlog and capital expenditure guidance.
Broader S&P 500 Earnings Growth Trajectory
Apart from the revaluation of technology stocks, underlying corporate metrics have been holding up very well. The blended earnings growth for Q3 2026 is +31.4% YoY, the third straight quarter with a growth rate exceeding the 25% mark. Top-line revenue growth is coming in at +14.3% YoY, while blended net profit margins have grown to 16.5%.
Inflation Print to Shape December FOMC Expectations
After the positive surprise in October NFPs (165k versus 59k expected), there is a shift in expectation of monetary policy among fixed income derivative markets.
As per the CME FedWatch Tool, there is a 75.5% chance that the Fed would raise the rates by 25 basis points at the December 9 FOMC meeting, taking the target range for the federal funds rate to 4.00%-4.25%. The CPI report on Tuesday (expected: +0.3% MoM headline, +0.2% core) and PPI on Friday would be significant markers.