WMT Q3 FY2027 Earnings Preview
The international retail powerhouse will announce its fiscal third-quarter results for 2027 before opening of the market today, with recent growth in the digital front and membership, offsetting by high valuation and high expectations.
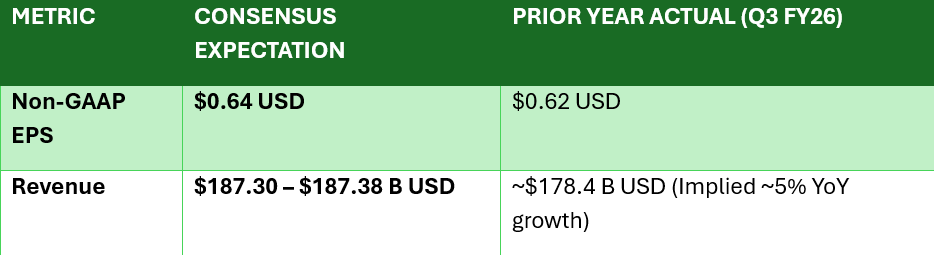
Analysts project revenue of $187.30 billion to $187.38 billion, growing around 5.0% from the previous year, with non-GAAP EPS of $0.64, which translates to a growth of 3.2% from $0.62 last year.
Key Takeaways:
E-Commerce and High-Margin Engines: There is growing investor interest in the alternative sources of revenue for Walmart. In Q2, sales of e-commerce operations went up by 23% year-over-year; sales of membership fees were up 17%; and revenues from high-margin advertising went up by 38%.
Market Share and Holiday Promotion Plans: Walmart continues increasing its market share among all classes of income driven by persisting inflationary trends. Under CEO John Furner, the retailer is going for fast fulfillment (launching the delivery of packages via drones at 300 locations), AI shopping bots, and three huge holiday promotions to December 2nd.
Valuation and Historical Pre/Earnings Reaction: WMT stock is priced at about 44.1x to 46.0x earnings (well above the peer group median multiple of ~16x). Though Walmart has beat or topped bottom line forecasts in each of its past four earnings announcements, shares have dropped in the three of those four quarters due to conservative guidance and valuation concerns.
Market Positioning Pre-Earnings: Walmart shares finished Wednesday trading at $127.36 (-0.13%), representing nearly 25% increase from the lows of the year and about 5.4% off its 52-week high point. The options market sees an implied move of about ±6.2% to 6.9%.
Digital Fulfillment & Alternative Revenue Streams Expected to Lift Q3 Sales
The Walmart growth model involving scale of stores with fast online delivery, Walmart+, and Walmart Connect and Vizio marketing is still the key reason for its topline growth. The analysts forecast a 2.9% increase in U.S. comparable sales (without fuel) for Q3. In the second fiscal quarter, the revenues increased by 5.9% to $187.9 billion.
WMT’s Operational Momentum Meets Tariff Normalization & Margin Scrutiny
Although the fundamental demand is strong for all three business divisions: U.S., International, and Sam's Club, the focus now is on profit margins following the Q2 gross margin (25.4%), which was boosted by one-off tariff refund payments. Moreover, the company has hinted at additional spending of $2+ billion dollars related to higher fuel costs and faster inventory growth (+6.7% YoY).
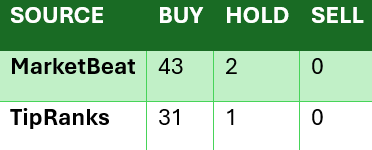
Analysts Expectation:
UBS Group analyst Michael Lasser maintained a Buy rating on Walmart and raised his price target to $149.00 (from $130.00), representing a +16.99% upside case.
Stifel Nicolaus analyst Michael Montani initiated coverage with a Buy rating and a $145.00 price target (+12.92% upside).
JPMorgan Chase analyst Christopher Horvers reiterated an Overweight rating and boosted his price target to $145.00 (from $125.00).
Bank of America Securities analyst Christopher Nardone reiterated a Buy rating with a $139.00 price target.
Wells Fargo analyst Edward Kelly maintained an Overweight rating while lifting his price target to $135.00 (from $120.00).
SHARIAH Compliance Metrics
Walmart Inc. (WMT) is classified as DOUBTFUL by Musaffa under its AAOIFI-based Shariah screening methodology as of November 19th, 2026 based on its Q2 fiscal 2027 earnings report.
Business Activity: 83.20% Halal, Doubtful is 16.75% and non-Halal is 0.05%
Interest-bearing securities and assets = 1.83% (Shariah-complaint is < 30%).
Interest-bearing debt = 7.95% (Shariah-complaint is < 30%).
You can get a more detailed breakdown of Walmart Shariah status on its stock page.
Analyst Ratings
Earnings Expectation