HD Q3 2026 Earnings Preview
The biggest home improvement specialty retailer in the world is ready to announce its fiscal third-quarter 2026 results ahead of the market opening on November 17, driven by the strong environment of demand for small maintenance activities, which contrasts with slow housing turnover.
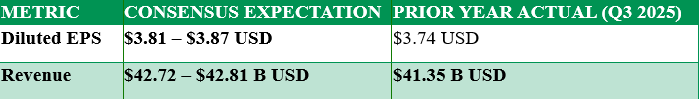
Analysts anticipate the company’s revenues at the level of $42.72 billion-$42.81 billion (+3.3%-3.5% year-over-year compared to $41.35 billion) and diluted EPS in the range of $3.81-$3.87 (+2.7%-3.5% YOY compared to $3.74 last year).
Key Takeaways:
Strength in Professional Contractor (Pro) Demand: The stock market analysts are tracking the performance of Pro demand which continues to beat DIY customers in building materials, tools, and repair. SRS Distribution strategic growth through the company's partnership through Mingledorff's and the HVAC vertical is a key growth strategy for Home Depot.
Housing Turnover & Margins: With housing turnover rates being very low and rising mortgage interest rates of around 7.4%, the big remodeling projects remain under pressure. In addition, it was noted by management that Q2 gross margin will be negatively impacted by incremental input and acquisition mix costs in Q3.
Peers and Sector Performance Comparison: Shares of Home Depot have increased 2.8% in the past three months and outperform both the S&P 500 (-2.8%) and Floor & Decor (-16.6%). However, its share price lags behind its peer companies, Lowe's (+4.1%) and Williams-Sonoma (+3.6%).
EPS Surprise and Stock Position: Home Depot has a positive Zacks Earnings ESP of 1.10% with a Zacks Rank #3 (Hold). It had a trailing four-quarter average earnings surprise rate of 2.9% (with a +4.5% surprise in Q2). The last trade was at $348.82 and it currently trades around 12.4% below its 52-week high of $397.63.
Pro Ecosystem & Digital Retail Investments Expected to Lift Q3 Sales
Funding for Home Depot's "One Home Depot" interconnected retail strategy that connects 2,364 retail stores and 1,340+ SRS locations with efficient digital logistics will lead to greater engagement among DIY and professional consumers. Estimates show that the company’s retail sales per store will come to $17.99 million (versus $17.55 million last year) and average retail ticket will be $92.24 (versus $90.39 in Q3 2025).
For fiscal Q2 2026, Home Depot reported $47.86 billion in revenue and $4.92 adjusted EPS (beating analyst forecasts by $0.19).
HD’s Core Retail Growth Meets Housing Sluggishness & Margin Compression
Whereas demand for small-scale maintenance and repair services is expected to remain unchanged, four years of low housing transaction rate have kept Home Depot from taking advantage of opportunities for larger and more profitable financed renovations. The company is predicted to register a slight decline in retail customer transactions to 390.97 million from 393.50 million last year. In addition, Home Depot's profitability will come under pressure in the short run due to weakening positive impacts of Q2 tariffs.
Analysts Expectation:
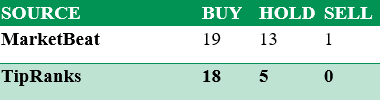
Home Depot maintained its Buy rating from UBS analyst Michael Lasser with a price target of $420.00.
The Buy rating from JPMorgan Chase analyst Christopher Horvers was also affirmed with a price target increase to $400.00 (from $396.00).
Home Depot also received a reiteration of the Buy rating from Bank of America Securities analyst Christopher Nardone with a price target of $397.00.
Another rating reaffirmed by Bernstein analyst Zhihan Ma is the Hold / Market Perform rating with a price target increase to $357.00 (from $344.00).
The price target of $322.00 (down from $346.00) and Hold rating from Stifel Nicolaus analyst W. Andrew Carter were based on the weak housing market.
SHARIAH Compliance Metrics
The Home Depot qualifies for all three Musaffa Shariah screening parameters based on AAOIFI methodology as of November 16th, based on its Q2 2026 earnings report.
Business Activity: 99.93%Halal, Doubtful is 0.00%, and non-Halal is 0.07%.
Interest-bearing securities and assets = 0.58% (Shariah-complaint is < 30%).
Interest-bearing debt = 14.77% (Shariah-complaint is < 30%).
You can get a more detailed breakdown of The Home Depot Shariah status on its stock page.
Analyst Ratings
Earnings Expectation