TSLA Q3 2026 Earnings Preview
Tesla is set to report third-quarter results after market close on Wednesday. FactSet analysts expect Tesla to report net income of $782.2 million, down from $1.37 billion a year earlier.
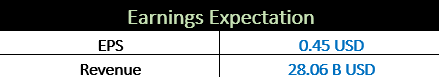
Earnings are forecasted at 45 cents per share, compared with 50 cents a year ago. Sales are expected to come to $28.06 billion, roughly flat year over year. Tesla shares have risen 1.4% over the past three months and were recently trading at $374.54.
Key Takeaways:
Vehicle deliveries exceeded expectations despite falling year over year. Tesla delivered 486,532 vehicles, a 2.1% decrease from Q3 2025’s record but above the 461,974 consensus.
Tesla continued to shrink its inventory. It produced 464,391 vehicles, 22,141 below the number of vehicles delivered, for a second consecutive quarter of reducing its inventory.
The company’s lineup continues to be dominated by Model 3 and Model Y. The two models accounted for 478,237 deliveries, while deliveries of other models fell 48% year over year to 8,295.
Energy storage and revenue outlooks are mixed. Storage utilization increased 9.6% year over year to 13.7 GWh but came up short of analyst expectations. Revenue is expected to be roughly flat year over year, even though deliveries and storage deployments exceeded those of Q2.
Margins, earnings, and cash flow are primary concerns. Analysts expect adjusted EPS of $0.45, down from $0.50 a year earlier. Tesla’s Q2 automotive margins deteriorated, regulatory-credit revenue decreased, and the company reported negative free cash flow; large 2026 capital expenditures can further strain cash flow.
Key Areas of Focus:
Tesla Investors Eye AI Breakthrough or Potential SpaceX Merger
Tesla shares have been relatively flat as investors are waiting for either a breakthrough in artificial intelligence or a potential merger with SpaceX. Elon Musk called a combination of the two companies “a good idea” and noted that special committees at both firms have been formed to explore the opportunity. SpaceX’s shares jumped 8% in after-hours trading on Tuesday.
SpaceX noted its first-ever profit as a publicly traded company. Elon Musk expects the annual recurring revenue of his rocket and spaceship company to exceed $500 billion and $1 trillion by 2027, fueled by a data-center capacity crunch and an explosion in AI demand.
Tesla Auto Revenue Expected to Decline as Investors Watch Margins and Pricing
Tesla’s Auto segment posted $22.2 billion in revenue in FY25 Q3, but FY26 Q3 revenue is expected to fall below $21 billion. With gross margin falling to 16.9% in the last quarter, investors will be looking to see if Tesla will continue to lower prices to retain market share during the expected slight decrease year-over-year and if gross profit will rebound.
Tesla Energy Storage Growth Slows as Deployments Miss Expectations
Tesla’s energy storage installations touched 13.7 GWh, which is an increase of 1.5% quarter-over-quarter and 9.6% year-over-year. However, the figures remained short of the expectations of analysts, who anticipated around 15.9 GWh.
In FY26 Q2, Tesla’s energy generation and storage segment’s revenue grew by 12.5% year-over-year to $3.139 billion. While the increase seems satisfactory, it appears that the company’s energy segment is unable to sustain such a growth rate. Although Megapack projects continue to drive revenue, it remains to be seen how far they will take the segment in the face of the cyclicality of the automotive market.
Services and Other Revenue Growth Faces a More Cautious Outlook
The company’s Services and Other revenue grew 50.4% year-over-year to $4.581 billion in FY26 Q2, supported in part by the expansion of its charging network. As a high-margin contributor, the segment’s ability to sustain growth could help stabilize overall profitability, though the market expects a slower pace in Q3, forecasting revenue of $4.29 billion, up 23.5% year-over-year.
Analysts Expectation:
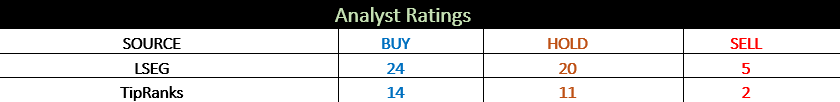
Cantor Fitzgerald analysts reiterated an Overweight rating and $485.00 price target on Tesla (TSLA).
JPMorgan analysts reiterated a Neutral rating and $415.00 price target on Tesla (TSLA).
Yorkville Ives analysts initiate coverage on Tesla (TSLA) with an Outperform rating and a price target of $500.00.
SHARIAH Compliance Metrics
TSLA qualifies for all three Musaffa Shariah screening parameters based on AAOIFI methodology as of October 2026, based on the Second Quarter 2026 report.
Business Activity 97.32% Halal, Doubtful is 0.00%, and non-Halal is 2.68%.
Interest-bearing securities and assets = 4.37% (Shariah-complaint is < 30%).
Interest-bearing debt = 0.91% (Shariah-complaint is < 30%).
You can get a more detailed breakdown of Tesla Shariah status on its stock page.
TSLA Q3 2026 earnings after market (4:07 pm ET) October 21, 2026