TGT Q3 2026 Earnings Preview
With high hopes due to strong stock performance in the first half of the fiscal year 2026, the retailing behemoth will post its third-quarter fiscal 2026 financials prior to opening bell.
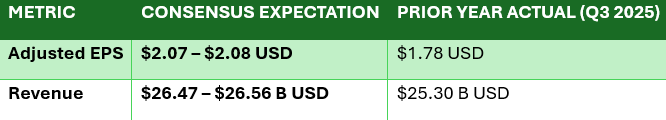
Analysts anticipate revenue between $26.47 billion to $26.56 billion, which is a 4.6% to 5.0% rise from $25.30 billion, and adjusted EPS between $2.07 and $2.08, a 16.3% to 16.9% growth from last year’s $1.78.
Key Takeaways:
Turnaround Direction & Holiday Guidance: The stock will be looking for CEO Mike Fiddelke’s turnaround efforts and essential Q4 holiday guidance (consensus stands at $2.69 in EPS on $31.82 billion in revenues). Options traders are expecting an implied move of around 8% to 9.1% up or down.
Customer Traffic Boost & Pricing Cuts: Target cut prices on more than 10,000 products to boost customer traffic despite ongoing inflation. Analysts estimate comp sales of 3.6% to 4.0% growth in Q3 after 3.8% in comp sales and 3.6% in traffic growth in Q2.
Earnings Quality & Normalizing Tariff Refunds: The headline earnings per share of Target for Q2 of $4.11 were lifted by $994 million or $1.65 in per share one-time tariff refunds. Given its full-year adjusted EPS outlook of $8.25-$9.25 (excluding refunds) or $9.90-$10.90 (including refund) analysts are looking at Target’s core margins.
Pre-Earnings Setup: Shares of Target were trading at $159.53 on Tuesday (-0.49%) after soaring by around 60%-70% so far this year.
Store Investments & Digital Fulfillment Expected to Lift Q3 Sales
In terms of strategic investments in enhancing store experience, AI-based tools for merchandising, and omnichannel order fulfillment, customer engagement has continued to be supported. For the quarter ending June 2026, Target recorded net sales of $26.5 billion, up 5.3% year-on-year due to an 8.7% rise in digital comparable sales and more than 25% in same-day delivery services.
TGT’s Core Essentials Growth Meets Discretionary & Competitive Headwinds
Whereas frequency-based segments keep their momentum, discretionary segments like apparel and home underperformed in the last few quarters. Moreover, Target is currently facing stiff competition with regards to pricing from Walmart and Amazon (where Target charges about 13% more for comparable products). In addition, high costs associated with labor and technology may hinder margins.
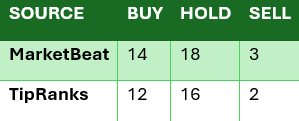
Analysts Expectation:
UBS Group analyst Michael Lasser reiterated a Buy rating on Target and raised his price target to $205.00 (from $185.00), representing a +28.50% upside case.
Jefferies Financial Group analyst Corey Tarlowe maintained a Buy rating with a $190.00 price target.
Wells Fargo analyst Edward Kelly reiterated a Buy rating with a $185.00 price target (+15.97% upside).
JPMorgan Chase analyst Christopher Horvers maintained a Hold / Neutral rating while boosting his target to $163.00 (from $157.00).
Stifel Nicolaus analyst Michael Montani initiated coverage at Hold with a $155.00 price target, citing concerns over heavy first-half spending translating into sustainable profit margins.
Barclays analyst Seth Sigman reiterated a Sell rating with a $147.00 price target (adjusted from $140.00).
SHARIAH Compliance Metrics
Target is classified as DOUBTFUL by Musaffa under its AAOIFI-based Shariah screening methodology as of November 18th, based on its Q2 fiscal 2026 earnings report.
Business Activity: 73.91%Halal, Doubtful is 25.14% and non-Halal is 0.95%.
Interest-bearing securities and assets = 9.74% (Shariah-complaint is < 30%).
Interest-bearing debt = 26.57% (Shariah-complaint is < 30%).
You can get a more detailed breakdown of Target Shariah status on its stock page.
Analyst Ratings
Earnings Expectation