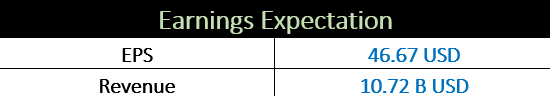
SNDK Q1 2027 Earnings Preview
The flash memory and storage company is poised to report first-quarter fiscal results in an upbeat environment after a strong rebound in memory prices.
Wall Street expects revenues of $10.72 billion, up 350% year over year, and earnings per share of $46.67, up from $1.22 a year ago.
Key Takeaways:
AI-related memory demand is boosting sentiment as investors watch demand for memory, NAND flash and enterprise SSDs ahead of SanDisk's earnings.
SK hynix saw operating profits rise 632% year-on-year to KRW 83.33 trillion and revenue rising 328% to KRW 104.62 trillion.
The company also had long-term contracts with customers, showing tight supply. It said it has contracts with 14 big customers for over half of its production capacity for 2027-2028. Demand is expected to exceed supply until 2030.
SK hynix's strong performance helped boost its peers in the memory sector. SanDisk shares were up around 4% on Wednesday.
SanDisk is set to report earnings soon. It will report fiscal Q1 2027 results on Oct. 29. Analysts are expecting EPS of $46.22 and revenue of $10.64 billion compared to $1.22 and $2.31 billion a year ago.
AI Infrastructure Growth Expected to Lift SNDK’s Data Center Revenue
The increased investments made towards building out AI infrastructures (specifically those for inferencing and agentic AI applications) have likely contributed towards increased demand for high capacity enterprise SSDs. The increased usage of TLC compute SSDs from the company's hyperscale customers and first-time shipments of its QLC-based Stargate platform could also have boosted SanDisk's data center revenues for the quarter.
SanDisk saw its data center revenues increase by 103% sequentially to $2.98 billion in fiscal Q4 2026.
SNDK’s Edge and Data Center Growth Meet Rising Competition
Higher storage needs in AI PCs, premium smartphones and connected devices, along with favorable NAND pricing, tight supply and long-term customer agreements, may support Sandisk’s growth. Edge revenue rose 48% sequentially to $5.43 billion in fiscal Q4 2026. In data centers, however, Sandisk faces mounting competition from Micron and SK hynix in enterprise SSDs and AI memory, and from Seagate, which is positioning HDDs as part of AI storage systems.
Analysts Expectation:
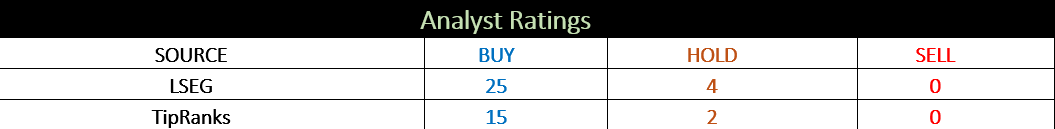
Mizuho analysts reiterated SanDisk to Outperform. The analysts also set a $2,050.00 price target for the stock.
A Citi analyst kept SanDisk (SNDK) rated as a buy with a $2.10K price target.
Wedbush analyst Matt Bryson has been boosting his estimates recently, expecting earnings of $11.45 billion in sales and $49.04 per share.
SHARIAH Compliance Metrics
SNDK qualifies all three Musaffa Shariah screening parameters based on AAOIFI methodology as of October 2026 annual report.
Business Activity 99.66% Halal, Doubtful is 0.01%, and non-Halal is 0.33%.
Interest-bearing securities and assets = 6.69% (Shariah-complaint is < 30%).
Interest-bearing debt = 0.00% (Shariah-complaint is < 30%).
You can get a more detailed breakdown of SanDisk Shariah status on its stock page.
SNDK Q1 2027 earnings after market (4:05 pm ET) October 29, 2026