QCOM Q4 FY2026 Earnings Preview
The semiconductor and wireless technology firm is due to release fourth-quarter fiscal 2026 financial results after market hours today. Wall Street is looking at a transition quarter due to increased input component costs and reduced allocation of Apple's modem.
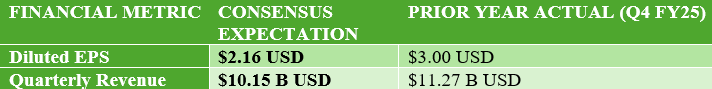
Analysts are predicting $10.15 billion in revenues, representing a decrease of 9.94% year-over-year, and diluted earnings of $2.16, indicating a decrease of 28.00% from $3.00 recorded a year ago.
Key Points:
The Non-Handset Diversification Tradeoff: Investors will be scrutinizing the execution of Qualcomm on its diversification pipeline in the absence of high-margin mobile chipset sales, which will be challenged by increased mobile DRAM/NAND memory prices and OEM bill of materials inflation.
Peer Group Performance: The global mobile and wireless peers group shows a polarized trend. Media Tech registered $5.25 billion (-17.00% YoY in mobile segment) while Broadcom's semiconductor revenue in Q3 was recorded at $16.7 billion (221% YoY). Skyworks had its revenue fall by -3.13% YoY to $0.93 billion.
Supply Chain Inflation & Advanced Node Costs: Costs for advanced sub-5nm wafer manufacturing (namely TSMC's N3E & 2nm process node) have been driving fabrication costs for its Snapdragon 8 Elite chipset. Increased memory cost shocks in consumer electronics have compelled the mid-tier mobile OEMs to reduce their build volumes.
Qualcomm Stock Sentiment: Qualcomm stock closed trading at $164.43 on Tuesday in anticipation of the report. Analysts are anticipating the company to post revenues of $10.15 billion with EPS of $2.16, which falls within management's guidance range of $9.70B - $10.50B revenue and $2.05 - $2.25 EPS.
Non-Handset Diversification Is Expected to Drive Long-Term Growth
Strategic investments in automotive digital cockpit, ADAS, and edge-AI compute platforms have led to an expansion of the multi-year pipeline. Qualcomm's Snapdragon Digital Chassis Design-Win backlog was recorded at $45.0 billion, beating Mobileye pipeline and expanding into its digital cockpit and ADAS deployments. Additionally, 42 OEM design wins for Snapdragon X Elite/Plus processor in Windows on ARM Copilot+ PCs have driven the adoption of edge-AI beyond traditional mobile avenues.
Qualcomm has seen QCT Automotive revenues expand to $1.59 billion in fiscal Q3 2026, up 61.00% year-over-year. IoT revenues increased to $1.83 billion (+9.00% YoY).
QCT Handset & Licensing Constrained By Supply Shortage and Internal Competition
High pricing of components such as DRAM and NAND memory, constrained supply chain, and elongated smartphone replacement cycle have kept the recovery of overall handset volume low. QCT Handset revenues were $5.09 billion in fiscal Q3 2026 (-15.45% QoQ, -20.00% YoY). QCT's in-house modem transition for flagship Android smartphones (C-series transition at Apple), Samsung Exynos internal allocations, and competition from Media tech's Dimensity 9600 Pro have posed challenges to licensing and mobile processor business segments.
Analysts' Expectations:
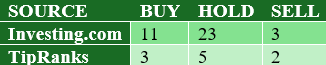
Bernstein analysts have revised down their short-term expectations, retaining a Hold rating with a $155.00 price target, citing high component costs and smartphone volume slowdown.
Street Consensus Average Price Target remains at mean price targets of $199 and $195, respectively, based on barchart.com and tipranks.com data against the last closing price.
Top Bull Case Price Target monitors a Street-high price target of $400.00, based on barchart.com data, on the basis of long-term automotive execution and quick Snapdragon X PC penetration.
SHARIAH Compliance Metrics
QCOM qualifies for all three Musaffa Shariah screening parameters based on AAOIFI methodology as of November 4th, based on its Q4 2026 earnings report.
Business Activity: 96.76%Halal, Doubtful is 0.00%, and non-Halal is 2.10%.
Interest-bearing securities and assets = 4.21% (Shariah-complaint is < 30%).
Interest-bearing debt = 8.72% (Shariah-complaint is < 30%).
You can get a more detailed breakdown of QCOM Shariah status on its stock page.
Analyst Ratings
Earnings Expectation