PANW Q1 FY2027 Earnings Preview
The world’s leading cyber security company is set to release its fiscal 2027 first quarter financials after the closing of the markets due to increasing enterprise needs of AI Security and company mergers.
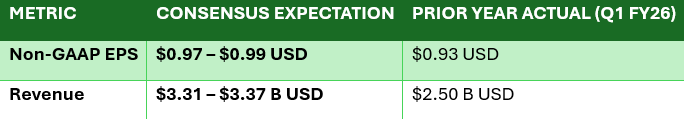
Analysts on Wall Street forecast revenue of between $3.31B and $3.37B, representing an increase of 32% to 35% compared to the year before of about $2.50B, and earnings of between $0.97 and $0.99, representing an increase of 4.3% to 6.5%.
Key Takeaways:
AI Security & NGS ARR Growth: Investors are fixated on the growth of Palo Alto Networks' Next Generation Security (NGS) Annual Recurring Revenue, estimated to expand 63% year-over-year to $9.54 billion-$9.56 billion. Prisma AIRS, the company's AI security solution, achieved over $100 million in ARR in less than four quarters since becoming generally available with more than 800 customers.
Platform Strategy & Acq. Synergy: The management's platform strategy including SASE, Cortex XSIAM and Network Firewalls is aided by the acquisitions of CyberArk and Chronosphere. Net new ARR and operating margins will be analyzed for their sustainability once the costs of the acquisition are included.
Positioning Ahead of Earnings & Options Setup: Shares of PANW closed at $309.29 yesterday (-2.15%) reversing about 26% off their record highs in early October at $419.91 although still up ~68% to 75% year-to-date. Option markets are implying an implied move of around ±11.5%.
Guidance Track Record: Previously, management had guided Q1 revenue to be $3.30 billion-$3.31 billion and non-GAAP EPS of $0.96-$0.98 along with FY2027 revenue of $14.10 billion-$14.20 billion and non-GAAP EPS of $4.16-$4.19. Future guidance will be key to price action after earnings.
AI Security & Platform Consolidation Expected to Lift Q1 Sales
The adoption of AI workloads migration into production has boosted the need for a holistic security platform. In Q4 2026, Palo Alto Networks recorded revenue of $3.41 billion (+34.5% YOY) where Subscription and Support revenue increased 36.2% YOY to reach $2.67 billion, whereas Product revenue grew 28.6% to $738 million. The RPO rose 34% YOY to reach $21.2 billion, whereas NGS ARR stood at $9.10 billion (+63% YOY).
PANW’s Growth Trajectory Meets Valuation & Competitive Scrutiny
Although PANW has beat analyst estimates for revenue and non-GAAP earnings per share in every quarter for the past two years, the stock has closed lower after five of its past six earnings announcements because Wall Street had already factored in guidance that was more conservative than the company reported. Looking ahead, there is concern about high valuations (~77x forward earnings), insider sales, and competing cybersecurity companies like CrowdStrike and Fortinet.
Analysts Expectation:
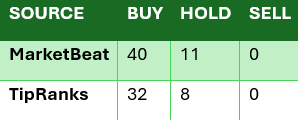
Wells Fargo analyst Michael Turrin reiterated an Overweight rating with a Street-high $525.00 price target (+69.74% upside).
Citi analyst Fatima Boolani maintained a Buy rating with a $440.00 price target, citing compelling risk-reward following the recent pullback.
TD Cowen analyst Shaul Eyal reiterated a Buy rating with a $440.00 price target.
Cantor Fitzgerald analyst Jonathan Ruykhaver maintained an Overweight rating with a $425.00 price target, highlighting platformization strength across SASE, XSIAM, and firewalls.
KeyBanc Capital Markets analyst Eric Heath upgraded PANW to Overweight from Sector Weight with a $380.00 price target, noting accelerating 2027 security budgets.
SHARIAH Compliance Metrics
Palo Alto Networks, Inc. qualifies for all three Musaffa Shariah screening parameters based on AAOIFI methodology as of November 18th, based on its Q4 fiscal 2026 earnings report.
Business Activity: 96.39% Halal, Doubtful is 0.00% and non-Halal is 3.61%.
Interest-bearing securities and assets = 6.92% (Shariah-complaint is < 30%).
Interest-bearing debt = 1.30% (Shariah-complaint is < 30%).
You can get a more detailed breakdown of Palo Alto Networks, Inc. Shariah status on its stock page.
Analyst Ratings
Earnings Expectation