NLST Q3 2026 Earnings Preview
The enterprise memory and storage subsystem supplier is poised to deliver its Q3 fiscal 2026 financial results today. Analysts expect a major turnaround in operations and a top-line boost due to memory shortages, AI-fueled demand, and patent agreements that will fundamentally change the financial profile of the business.
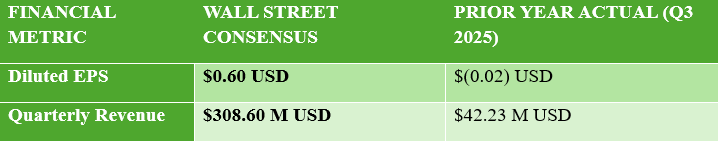
The consensus estimate for revenue is $308.60 million, up ~630.8% y-o-y, with earnings per share at $0.60 versus a loss of $(0.02) per share last year.
Key Takeaways
Demand from AI and Top-Line Growth: The current Q3 revenue consensus for NLST is estimated at $308.6 million, fueled by structurally under-supplied memory markets and positive pricing dynamics. First half 2026 revenue totaled $214.7 million (around 3 times higher than last year) resulting in gross profit of $45.3 million.
Transformational IP Partnerships: Strategic litigation settlements significantly change the risk profile of NLST. Five-year alliance with Samsung concluded in August 2026 includes a one-time licensing payment of $200 million, up to $27.5 million in quarterly royalties, and $300 million annual DRAM/NAND supply agreement. Alliance with Micron Technology signed in October 2026 brought $600 million in total payments starting Q4 2026.
Product Ramp-Up of Agentic AI Workstations: Besides the sale of memory components, Netlist is scaling the company's proprietary LIGHTNING platform, which includes Ultra-Low Latency DDR5-6000 and DDR5-6400 RDIMMs optimized for Agentic AI applications, as well as testing CXL NVvault solutions in collaboration with OEM and hyperscaler customers.
Valuation and Valuation Ratios: NLST shares closed at $6.26 as of November 9, 2026, after climbing 123.5% over the last six months. The stock currently trades at a forward P/E of ~6.85 despite having a GF Value™ of $2.40 and a GF Score™ of 49/100 as a result of solid balance sheet metrics (Altman Z-Score of 24) offset by net insider sales of $2.1 million in 12 months.
AI Infrastructure Demand and Strategic Partnerships Drive Revenue Dynamics
Structural under-supply in global DRAM and NAND markets, along with investments in AI and high-performance computing infrastructures, are creating positive top-line dynamics. Netlist has grown its revenue footprint through proprietary high-density memory modules and strategic access to memory component supply.
In the second quarter of 2026, Netlist's revenues stood at $109.80 million, growing 163% YoY. According to management comments in the last earnings call, revenues from product sales in Q3 are expected to be roughly similar to the Q2 levels before taking into account major licensing revenues.
Supply Chain Vulnerabilities and Market Dynamics
Despite favorable demand in servers powered by AI, Netlist remains exposed to sector competition and dependence on memory component providers. The company's strategic supply agreement with Samsung, which includes purchases of up to $300 million annually of DRAM and NAND products, gives Netlist access to necessary inventories to serve system builder and hyperscale customer demands through memory supply choke points.
Analysts' Expectations and Price Targets
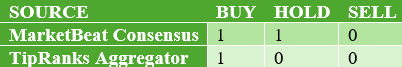
Coverage Consensus Rating: Rated as a Moderate Buy by coverage analysts.
Average Price Target: At $15.00, implying +140.00% to +163.16% upside potential against recent price range.
Earnings Whisper and Rank: Bears a Zacks Rank #2 (Buy) with an Earnings ESP of 0.00%.
SHARIAH Compliance Metrics
NLST qualifies for all three Musaffa Shariah screening parameters based on AAOIFI methodology as of November 9th, based on its Q2 2026 earnings report.
Business Activity: 99.64%Halal, Doubtful is 0.00%, and non-Halal is 0.36%.
Interest-bearing securities and assets = 10.18% (Shariah-complaint is < 30%).
Interest-bearing debt = 0.70% (Shariah-complaint is < 30%).
You can get a more detailed breakdown of NLST Shariah status on its stock page.
Analyst Ratings
Earnings Expectation