MU Q4 2026 Earnings Preview
Micron Technology (MU) is heading into its fiscal fourth-quarter earnings report amid heightened expectations after its stock surged approximately 270% this year.
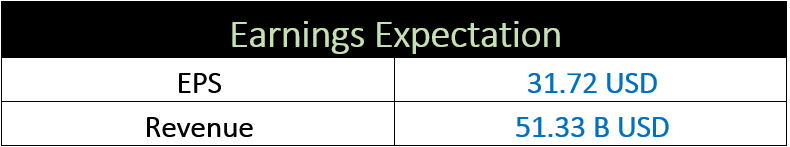
Analysts anticipate quarterly revenue of $50.75 billion, a substantial increase from $11.31 billion in the year-ago period. The forecast would represent a new company record, surpassing the $41.46 billion generated in the fiscal third quarter. Micron has exceeded Wall Street’s revenue estimates for 12 consecutive quarters.
Fourth-quarter earnings are projected at $31.45 per share, compared with $3.03 a year earlier. The company has also beaten consensus EPS estimates for 10 consecutive quarters, highlighting its strong track record of execution.
Key Takeaways:
Micron’s valuation has soared: Shares are up 261% year to date and more than 560% over the past 12 months, pushing the company’s market capitalization above $1 trillion ahead of its fiscal fourth-quarter earnings report.
AI demand is driving record growth: A memory-chip shortage fueled by expanding AI infrastructure has propelled Micron’s revenue into the tens of billions and capped a year of exceptional earnings performance.
Investors are focused on durability: With much of Micron’s strong performance already reflected in its stock price, the key question is no longer how powerful growth can be, but how long it can continue.
Analysts see a potentially prolonged memory cycle: Morgan Stanley expects tight market conditions to persist despite new supply, while D.A. Davidson believes investors may be underestimating the cycle’s longevity. Analyst Gil Luria views demand for GPUs, CPUs and memory as part of one extended AI-driven growth cycle.
Long-term contracts improve revenue visibility: Micron has secured roughly $100 billion in binding, multiyear HBM take-or-pay agreements and more than $22 billion through 16 strategic customer commitments, reducing its exposure to volatile spot pricing.
Inside the Memory Crunch: The AI Boom Fueling a New Era for Memory Chips
Micron’s rally has been driven primarily by the rapid expansion of AI infrastructure, which is creating unprecedented demand for advanced memory products. The global DRAM and NAND markets are highly concentrated, with three major manufacturers accounting for the vast majority of worldwide supply.
Micron reported record fiscal third-quarter revenue of $41.46 billion, an approximately 345% increase from the year-earlier period. The strong performance was supported largely by robust demand for high-bandwidth memory (HBM), which is essential to the continued expansion of Nvidia’s AI accelerator ecosystem.
During its fiscal third-quarter earnings call, Micron indicated that a substantial portion of its HBM production capacity had already been committed through calendar 2027 and into 2028. The company has since announced approximately $100 billion in binding, multi-year HBM take-or-pay agreements.
Micron has also entered into 16 strategic customer agreements representing more than $22 billion in cash and cash-equivalent commitments, with many extending through 2030. These arrangements provide greater revenue visibility and reduce the company’s exposure to short-term fluctuations in memory pricing and demand.
Collectively, the agreements signal a significant evolution from the memory industry’s traditionally volatile, boom-and-bust spot-market model toward a more predictable, infrastructure-oriented business. DRAM spot prices have risen approximately 52% since January, while Micron has begun high-volume shipments of HBM4, manufactured using its 1-beta DRAM process, for Nvidia’s forthcoming Vera Rubin platform. Analysts expect the full financial benefits of this strategic transition to become more apparent in fiscal 2027 than in the company’s upcoming earnings report.
Analysts Expectation:
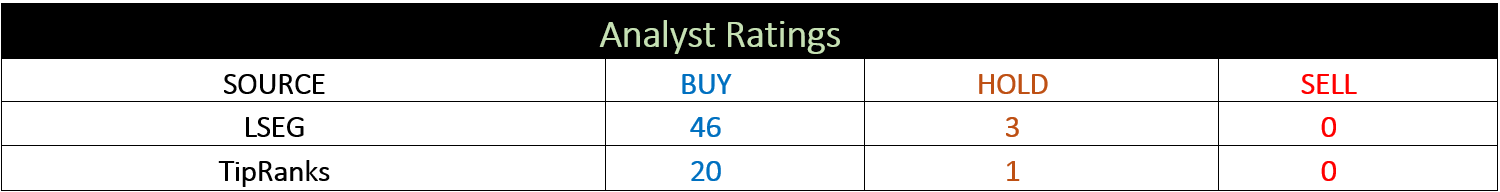
Baird raised its price target for Micron Technology (MU) to $1,520, up from $1,280, while maintaining its Outperform rating.
D.A. Davidson reiterated its Buy rating and kept its $2,000 price target unchanged.
JPMorgan reaffirmed its Overweight rating and maintained its $1,540 price target for Micron.
SHARIAH Compliance Metrics
Micron qualifies for all three Musaffa Shariah screening parameters based on the AAOIFI methodology as of the Q4 2026 report.
Business Activity 99.36% Halal, Doubtful is 0.00%, and non-Halal is 0.64%.
Interest-bearing securities and assets = 14.42% (Shariah-complaint is < 30%).
Interest-bearing debt = 2.74% (Shariah-complaint is < 30%).
MU Q4 2026 earnings after market (4:01 pm ET) September 30, 2026