KLAC Q1 2027 Earnings Preview
Semiconductor manufacturing equipment company KLA Corporation (KLAC) reports earnings this afternoon.
The company posted revenue of $3.66 billion in its latest quarter, up by 15.2% year-on-year. It exceeded analysts' forecasts and reported higher earnings per share and operating income than expected.
Key Takeaways:
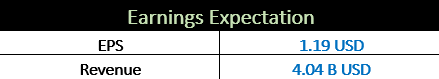
Revenue is expected to increase by 25.8% YoY to $4.039 billion for the quarter ended September 30, 2026, compared with $3.21 billion compared to last year.
This is in line with the company’s guidance range of $3.80 billion to $4.20 billion.
Analysts expect earnings to be $1.18 per share, within the company’s guidance range of $1.06 to $1.26. This has remained the same over the last three months.
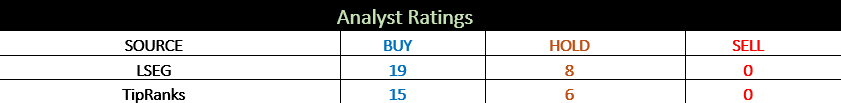
There is generally positive sentiment from analysts, with 19 "Strong Buy"/"Buy" ratings, eight "Hold" ratings, and no "Sell"/"Strong Sell" ratings.
The median 12-month price target sits at $227.00, about 52.1% above the stated last closing price of $149.21. KLA has guided that gross margin will be between 61.5% and 63.5%.
AI Demand and Advanced Packaging in Focus
KLA Corporation (KLAC) provides process control, enabling, and yield management solutions to semiconductors and related electronics markets. The company has a market cap of $213.3 billion and is scheduled to report fiscal first-quarter 2027 results after the market closes on Wednesday, Oct. 28. Analysts expect diluted earnings of $1.18 increase of 34.1% from $0.88 in the last year. It has exceeded or matched consensus estimates in each of the past four quarters.
Analysts expect an increase in earnings per-share in fiscal 2026 to $5.43, a 44.4% increase from $3.76. They expect earnings to continue growing by 22.1% to $6.63 in fiscal 2028. Over the last 52 weeks, the stock has risen by 40%, beating both the S&P 500 Index (up 15.2%) and the State Street Technology Select Sector SPDR ETF (up 29.5%).
The company has been performing well due to increasing demand in AI infrastructure and advanced packages. CEO Rick Wallace has noted that AI spending is accelerating, high-end foundry and logic demand and increased process control intensity. Control of advanced packages is forecasted to increase by over 70% to around $1.1bn due to HBM and hybrid bonding. Services are also seeing good growth, with 80% of revenue contracted. PCB and Specialty have seen growth in excess of 25%. However, CFO Bren Higgins expects growth to accelerate in the second half of the year as new capacity comes online. Investors will be keen to see how the company handles supply issues and a negative margin of over 100 basis points due to memory prices.
Analysts Expectation:
Morgan Stanley analysts lowered the price target on KLA Corporation (KLAC) to $227.00 (from $253.00) while maintaining an Overweight rating.
An analyst from UBS maintained KLA Corp (NASDAQ: KLAC) at ’neutral’ with a price target of $200.00 from a prior price target of $215.00.
An analyst from Berenberg maintained KLA Corp (NASDAQ: KLAC) at ’buy’ with a price target of $230.00 from a prior price target of $2.00K.
SHARIAH Compliance Metrics
KLAC qualifies all three Musaffa Shariah screening parameters based on AAOIFI methodology as of the October 2026 annual report.
Business Activity: 98.46% Halal, Doubtful is 0.00%, and non-Halal is 1.54%.
Interest-bearing securities and assets = 4.00% (Shariah-complaint is < 30%).
Interest-bearing debt = 4.43% (Shariah-complaint is < 30%).
https://musaffa.com/stock/KLAC/ for a more detailed view.
KLAC Q1 2027 earnings after market (4:05 pm ET) October 28, 2026