HIMS Q3 2026 Earnings Preview
The consumer telehealth company is set to report third-quarter earnings after the market closes. Analysts expect a good top line revenue growth but at the expense of gross margins.
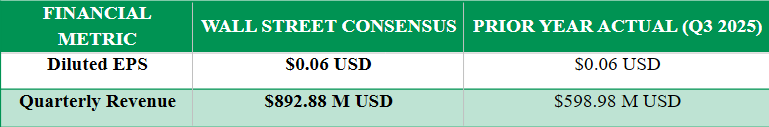
Analysts forecast earnings for the quarter to be $892.88 million, representing a 49.07% increase year over year, and diluted earnings per share of $0.06, which will remain the same compared to last year.
Key Takeaways
Branded GLP-1 Shift & Margin Impact: However, investors are analyzing HIMS' shift in operations from manufacturing weight-loss drugs through compounding to the high volume retail storefront of its brands such as Zepbound by Eli Lilly and Wegovy by Novo Nordisk. Despite top-line growth remaining strong, growth in branded products leads to reduced gross margin at ~63.80%.
Peer Group Benchmarks: The consumer telehealth market reflects conflicting trends. LifeMD (LMDX) provided Q3 earnings forecast for $48.80 million, whereas Teladoc Health (TDOC), a traditional player, earned $605.10 million (-3.40% YoY) in Q3, as they shifted their focus from cash-pay direct-to-consumer products to insurance-driven business model.
Regulatory & Marketing Scrutiny: HIMS faces elevated regulatory headwinds, including FTC compliance scrutiny surrounding subscription onboarding funnels and ongoing state-level Corporate Practice of Medicine (CPOM) structural compliance across its MSO framework.
Pre-Earnings Market Positioning: Hims & Hers closed trading at $25.70 last Monday before the print. The analysts expect revenue to hit $892.88M (YoY +49.07%) and an EPS of $0.06, with 12 revenue estimate upgrades prior to earnings print.
Subscriptions & Branded Weight Loss Expansion Lift Q3 Sales
The rise in demand for personalized health solutions and weight loss management has fast-tracked the adoption of the platform. The structural distribution deals including access to Eli Lilly’s brand Zepbound and oral companion have widened the TAM for HIMS while shielding from any FDA 503A/503B compounding phase outs.
Hims & Hers has grown its active subscriber base to 2.89 million subscribers, resulting in $85.00 million in Q3 Adjusted EBITDA.
Core Digital Health Growth Met by CAC Inflation & Pricing Risks
The continued high customer acquisition cost (CAC) in Meta and Google advertising platforms along with deflationary pressures arising out of Amazon Pharmacy is expected to remain an impediment to increasing the margin. Additionally, commoditization in verticals such as Dermatology and Sexual Health will necessitate cross-sell programs (e.g. TRT, custom oral care) to combat churn.
Analyst Expectations & Price Targets
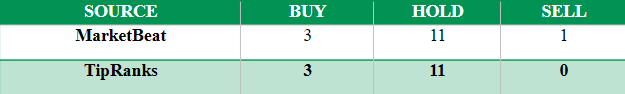
Needham & Company: Reiteration of Buy rating with a price target increased to $42.00 (from $35.00) based on the subscription growth in multiple conditions.
Barclays: Reiteration of Overweight rating with a price target of $35.00 due to impressive revenue growth trajectory, which is hampered by the pressure on the gross margin.
Citigroup: Maintenance of a Neutral rating with a price target of $33.00 due to excellent sales execution amid regulatory and marketing scrutiny.
SHARIAH Compliance Metrics
HIMS qualifies for all three Musaffa Shariah screening parameters based on AAOIFI methodology as of November 9th, based on its Q2 2026 earnings report.
Business Activity: 98.99%Halal, Doubtful is 0.00%, and non-Halal is 1.01%.
Interest-bearing securities and assets = 13.98% (Shariah-complaint is < 30%).
Interest-bearing debt = 22.69% (Shariah-complaint is < 30%).
You can get a more detailed breakdown of HIMS Shariah status on its stock page.
Analyst Ratings
Earnings Expectation