CSCO Q1 FY2027 Earnings Preview
This global leader in network and enterprise security is set to announce its Q1 fiscal 2027 financials post-market hours, as the company battles with a delicate mix of high AI infrastructure demand and short-term pressure on gross margins.
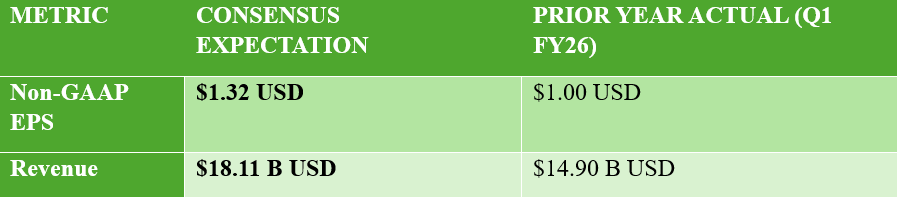
Analysts predict sales of $18.11 billion, representing a YoY growth of ~21.7%, and non-GAAP EPS of $1.32, registering ~32% growth compared to $1.00 in Q1 fiscal 2026.
Key Takeaways:
AI Infrastructure & Hyperscale Progression: The market is looking to see how Cisco makes progress towards its $7.5B annual target for AI infrastructure revenues for FY2027 (almost double the ~$4 billion reported in FY2026), driven by success stories with Silicon One and optical design wins expanding beyond hyperscalers.
Gross Margin & Mix Review: While consistently exceeding earnings estimates over the last four quarters, stock price movements have been tied to profitability and forward expectations. Cisco saw its non-GAAP gross margin come in at 66.3% in Q4 FY2026, down from 68.4% a year ago amid increased proportion of hyperscaler hardware with lower margins and rising costs for memory components.
Order Pull-Forward & Guidance Dynamics: With the company’s stock price down about 14% over the last month on concerns about Morgan Stanley pointing out possible order pull-forwards ahead of price increases, the focus now is on the company’s order stability. FY2027 full-year guidance is at this time set at $72.2B-$73.4B in revenues and $5.05-$5.11 in non-GAAP EPS.
Pre-Earnings Market Dynamics: As of Wednesday close, Cisco shares were quoted at $100.76 (+2.66%). With consensus estimates calling for $18.11 billion in revenues and $1.32 in EPS, both figures comfortably fall inside Q1 guidance of $18.0B-$18.2B in revenues and $1.32-$1.34 EPS.
AI Networking & Order Backlog Expected to Lift CSCO’s Core Product Revenue
AI data center build-outs by enterprises and hyperscalers have driven eight consecutive quarters of networking order growth in double digits. Progress in Cisco’s Silicon One technology and fast-optical networking technology is driving topline growth, with Cisco’s management aiming for $7.5 billion in fiscal 2027 AI infrastructure revenue from hyperscalers.
Cisco witnessed a sharp growth in the revenues from its Networking segment in fiscal Q4 2026 by 28% on a year-on-year basis (with fiscal 2026 networking revenues growing by 22% to $34.7 billion), and a rise in total orders by 35% on a year-on-year basis, including AI infrastructure orders worth $4 billion.
CSCO’s Software & Margin Profile Meet Hardware Mix Headwinds
While Security revenue grew 14% in Q4 FY2026 and Collaboration rose 12%, management noted that security growth is expected to normalize toward the high single digits following large Splunk deal contributions. Simultaneously, Cisco faces near-term gross margin compression (guided to 65%–66% for Q1 FY2027) due to rising memory prices, an increasing mix of lower-margin hyperscale hardware, and potential order pull-forwards ahead of price hikes.
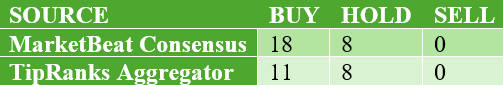
Analysts Expectation:
Bank of America Securities analyst Tal Liani kept a Buy rating on Cisco at $150.00 on account of steady network demand driven by AI.
Analysts at Rosenblatt have a Street-high price target of $165.00, whereas Truist has a price target of $140.00 on tailwinds from networking supercycle.
Morgan Stanley downgraded Cisco to Equal-weight from Overweight and reduced target to $120.00 from $135.00 owing to gross margin headwinds and risks related to forward orders.
Peter Weed, Bernstein analyst, reiterated Hold rating with price target of $110.00.
SHARIAH Compliance Metrics
CSCO qualifies for all three Musaffa Shariah screening parameters based on AAOIFI methodology as of November 12th, based on its Q4 2026 earnings report.
Business Activity: 96.53%Halal, Doubtful is 2.15%, and non-Halal is 1.32%.
Interest-bearing securities and assets = 8.80% (Shariah-complaint is < 30%).
Interest-bearing debt = 10.88% (Shariah-complaint is < 30%).
You can get a more detailed breakdown of CSCO Shariah status on its stock page.
Analyst Ratings
Earnings Expectation