Apple Inc. (AAPL) Fiscal Q4 2026 Earnings Preview
Apple Inc. is set to announce fiscal fourth-quarter 2026 results after market close today. This print is marked by a noteworthy transition as incoming Chief Executive Officer John Ternus prepares to give his first-ever earnings call remarks with CFO Kevan Parekh.
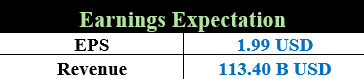
Wall Street analysts expect Apple to report quarterly revenue of $113.40 billion (+10.67% YoY) and diluted EPS of $1.99 (+7.57% YoY), putting the tech giant near the high end of its 9% to 11% guidance range.
Key Takeaways & Industry Macro Context
Leadership Transition Focus: Attention will be paid to the operational remarks made by CEO John Ternus following the departure of Tim Cook.
The AI Memory Cost Spike: A global spike in DRAM and NAND input cost (approximately 350% YoY) caused by the aggressive construction of hyperscale AI data centers has hurt the worldwide hardware segment. Budget brands like Xiaomi and OPPO have been hit by sharp margin contraction and severe decline in shipment volume. However, thanks to vertical integration and bulk purchasing power, Apple has succeeded in preserving the baseline gross margin (guide 47.0% to 48.0%).
Market Segment Duopoly: Global smartphone shipment volume fell 20% to 22% YoY in calendar Q3 2026 (preliminary data from IDC/Omdia). In spite of the total volume contraction, Apple managed to hold its global shipment market share at 22.4% (57.3M shipment units), growing in tandem with Samsung at the expense of severe slowdown of budget OEMs in emerging countries.
Pre-Orders & Product Composition: The current quarter's earnings reflect the initial launch-week shipment figures of the iPhone 18 Pro family, Apple Watch Series 12, and AirPods 5. Given the premium price positioning and carrier financing, the elongation of consumer replacement cycles (on average, 42–44 months in Western markets) is compensated by it.
Supply Chain & Component Cost Inflation
Currently, the worldwide hardware industry is experiencing challenging supply chain conditions amid 350% YoY input price increase caused by the rapid artificial intelligence data center infrastructure expansion, resulting in the absorption of all available wafer supply by data centers and shrinking in mobile memory production capacity. Although mass-market and budget-oriented Original Equipment Manufacturers face severe margin contractions and shipment volume declines in response to it, Apple's scale and vertical integration offer significant protection in terms of profitability. As a result, Apple successfully protected its profitability baseline and guided towards a healthy corporate gross margin of 47.50%.
Market Share Resilience & Segment Dynamics
In spite of the global industry downturn that included 20% to 22% year-over-year contraction in global Q3 smartphone shipment volume (the lowest level in the third quarter since 2013), Apple still demonstrates strong market share sustainability. Apple has managed to sustain its global shipment market share at 22.4%, shipping 57.3M units and capturing market share along with Samsung, while other players suffer from severe contraction. Entering the earnings print, Apple's operations depend heavily on its hardware (expected revenue of $56.48B to $56.54B from the sales of the iPhones) and its highly profitable Services division ($31.56B to $31.58B gross margins >70%).
Analyst Expectations
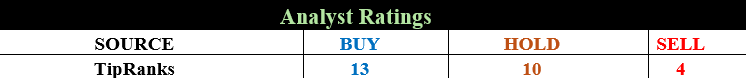
Dan Ives (Wedbush) – Outperform, $400.00 Target: Apple's massive consumer AI ecosystem will fuel a massive hardware replacement cycle as ~375 million iPhones overdue for an upgrade globally.
Mark Newman (Bernstein) – Buy, $370.00 Target: Competitive isolation and market share sustainability of Apple even in tough macro industry environment for the premium segment.
Samik Chatterjee (JPMorgan) – Overweight, $360.00 Target: Multi-quarter hardware replacement tailwind post-launch week interest.
Ananda Baruah (Loop Capital) – Downgrade to Hold, $330.00 Target: Recent downgrade triggered by channel tracking that confirmed 10% base unit reduction (~13M units cut from H2 2026 forecasts) due to memory and processor supply constraints.
Edison Lee (Jefferies) – Underperform, $263.66 Target: Skepticism about rich valuations and unit contraction with delayed core AI features.
SHARIAH Compliance Metrics
AAPL qualifies for all three Musaffa Shariah screening parameters based on AAOIFI methodology as of November 2nd, based on its Q3 2026 earnings report.
Business Activity: 95.66%Halal, Doubtful is 0.00%, and non-Halal is 4.34%.
Interest-bearing securities and assets = 4.27% (Shariah-complaint is < 30%).
Interest-bearing debt = 2.50% (Shariah-complaint is < 30%).
You can get a more detailed breakdown of AAPL Shariah status on its stock page.
AAPL Q4 2026 earnings after market (4:30 pm ET) November 02, 2026