AMD Q3 2026 Earnings Preview
Advanced Micro Devices, Inc. (AMD) is slated to release its Q3 2026 financial results post-market close. Due to strong AI adoption trends, cloud compute demand, and continued market share gain in the x86 servers category, the company should show a robust expansion in scale on the top and bottom line.
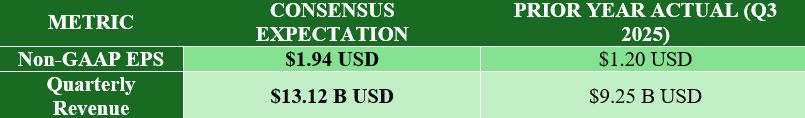
According to Wall Street expectations, the Q3 FY2026 revenue of AMD will be $13.12B (+41.84% YoY vs. $9.25B in Q3 2025). Non-GAAP EPS of AMD for Q3 FY2026 is expected at $1.94 (+61.67% YoY from $1.20 in the same period last year).
Key Takeaways
Scale in Data Center: The key focus for Wall Street analysts will be the fast growth rate of AMD's Data Center business segment. The expected revenue is seen expanding ~88% to 91% YoY, reaching $8.19B to $8.30B, driven by market share gains for EPYC CPUs and deployment of the Instinct MI300/MI325X platforms across hyperscalers.
Migration to x86: According to Mercury Research, AMD's x86 server CPU unit share rose to 34.5% (+7.3 points YoY) and revenue share increased to an all-time high 46.2%, bringing AMD closer in terms of revenue and financial scale in the core enterprise server sockets market with Intel.
Peer Financial Benchmarks: High demand in the sector lifts the revenues of other companies. NVIDIA reported Q2 FY2027 revenue of $96.20B (+117% YoY in Data Center), while Intel reported Q3 2026 data center revenue of $7.32B (+77.8% YoY) from depressed prior-year base.
Supply chain & packaging dynamics: Wall Street analysts are paying attention to the allocation of TSMC's 2nm and 3nm nodes, as well as the CoWoS packaging capacity. Although the cost inflation in the HBM3e memory components is still in place, long-term agreements with hyperscalers – for example, AMD GPU deployment by Anthropic – create multi-year revenue visibility.
AI Infrastructure & Server CPU Growth Drives Expansion in Data Center Revenue
With increased investments in AI training, inferencing, and cloud infrastructure, the demand for AMD's compute architectures is growing. Strategic adoption of AMD products in Microsoft, Meta, Oracle, as well as deployment of the next-generation Venice EPYC server CPU architecture on TSMC advanced nodes, helps AMD penetrate tier-1 data centers.
The Q2 FY2026 revenue of AMD's Data Center business segment reached $6.72 billion, or 16.26% sequential growth and 107% year-over-year growth. Data center revenues made up 58.23% of total net sales in Q2 FY2026.
Client & Embedded Segments Recovery Faced By Gaming Cyclical Challenges
In the consumer computing segment, revenue of AMD's Client segment increased by 5.88% sequentially to $3.06B (+23% YoY) in Q2 FY2026 due to the traction for Zen 5 desktop CPUs and deployment of the XDNA 2 NPU AI PCs (>50 TOPS). The revenue of the company's Embedded segment stabilized at $977M (+12.64% QoQ) due to normalization of the inventories across the industrial channels.
However, AMD faces challenges in its Gaming segment, with its Q2 FY2026 revenue declining by 31% year over year to $779M due to the late-cycle semi-custom SoCs demand adjustment for PlayStation 5 and Xbox Series X/S consoles. Also, NVIDIA is defending its software moat with CUDA and NVLink ecosystem, and Qualcomm and ARM-based architectures continue increasing their footprint in low power client sockets.
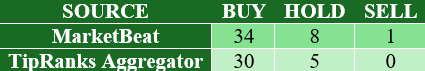
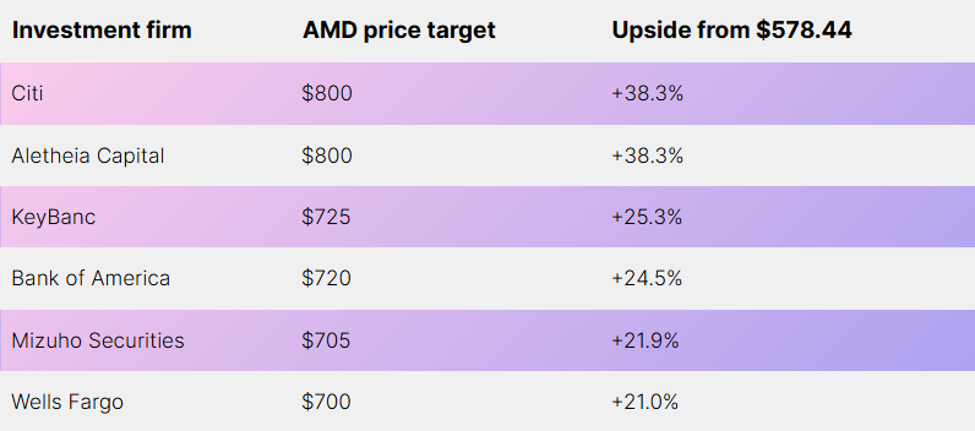
Analyst Expectations
A photo of beinsure.com
SHARIAH Compliance Metrics
AMD qualifies for all three Musaffa Shariah screening parameters based on AAOIFI methodology as of November 3rd, based on its Q2 2026 earnings report.
Business Activity: 96.76%Halal, Doubtful is 2.52%, and non-Halal is 0.72%.
Interest-bearing securities and assets = 4.41% (Shariah-complaint is < 30%).
Interest-bearing debt = 1.06% (Shariah-complaint is < 30%).
You can get a more detailed breakdown of AMD Shariah status on its stock page.
Advanced Micro Devices, Inc. (AMD) Q3 2026 Earnings 4:15 PM ET (After Market Close), Tuesday, November 3, 2026